Most people spend a fair amount of time on the loan application itself, the documents, the eligibility check, and the back-and-forth. Once the sanction letter arrives, there is often a moment of relief followed by a practical question: what actually happens now? The post-sanction process is something borrowers tend to know less about than the application stage, and that gap sometimes leads to confusion around timelines and paperwork that could otherwise be handled smoothly with a little context.
Between Sanction and Disbursement
A sanction letter is not the same as money in hand. It serves as an in-principle approval indicating that the loan amount is approved, pending a few final checks. Then follows the final document verification stage, where the lender reviews your papers: identity proof, address proof, income documents, and details of the car being purchased. If the vehicle is new, the dealer invoice and booking confirmation come into the picture here. For a used car, the registration certificate (RC) and an inspection report are added to the list. This part of the process moves much faster when all documents are ready in one place, which is worth organizing before the sanction stage even begins.
People assume the sanction covers everything and that the car will be ready within a day or two, when the actual timeline depends on how clean the documentation is and whether the lender needs any clarification.
Loan Agreement and What It Contains
Once the documents are clear, the lender draws up the loan agreement. The loan is laid out in a formal contract that specifies the loan amount, the interest rate, the repayment tenure, the EMI amount, and any applicable charges. Reading through this before signing matters more than most borrowers expect. The agreement also outlines what happens in case of a missed payment, the prepayment terms if someone wants to close the loan early, and the lender’s right over the vehicle until the loan is fully paid off.
For a car loan of any size, the agreement stage is where all the verbal or digital discussions become legally binding, so it is the right moment to raise questions rather than after the fact.
Mahindra Finance follows a clear process at this stage and keeps the borrower informed about each requirement rather than leaving them to follow up on their own.
Disbursement and What Comes After
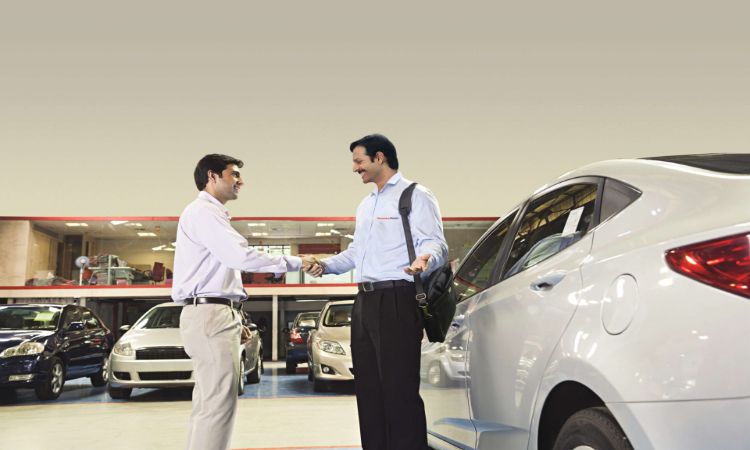
Once the agreement is signed, disbursement follows. For the purchase of a new car, the loan amount is directly transferred to the dealer rather than to the borrower’s bank account. For a used car purchased through a private transaction, the process may involve disbursing funds directly to the seller or owner after verifying the transfer documents. The car gets delivered after the dealer or seller confirms receipt of funds and completes their end of the paperwork.
After delivery, hypothecation is added to the vehicle’s registration certificate. This is a legal endorsement showing that the lender has a financial interest in the car until the loan is closed. It appears on the RC smartcard and stays there until the loan is fully repaid and a No Objection Certificate (NOC) is issued by the lender. This step sometimes catches first-time borrowers off guard, as the RC they receive lists the lender as the hypothecated party rather than showing unencumbered ownership.
EMI payments begin from the date mentioned in the agreement, which is usually within thirty days of disbursement. Using a car loan EMI calculator before this stage gives a clear picture of exactly what the monthly outflow will look like, so there are no surprises once the first due date arrives.
The post-sanction journey is short in most cases, but knowing each step in advance takes away the uncertainty that often makes it feel longer than it is.